Record Nasdaq. Muse Bit Back.
Nasdaq printed a second straight record at 27,244.28 while cash voted a flat S&P at 7,764.64. Muse’s bid flipped into competition fears on Schwab and travel names. Banks led losers. Brent settled $99.25. Path still inherits 3.75%–4.00%.
Tuesday, September 22, 2026
Morning Prep asked whether Monday’s settle would hold when speakers opened — overnight inside the new daily 1SD on ES and NQ, weekly already through +1SD, oil soft, Williams then Jefferson as plumbing not a re-vote. Cash answered with a flat S&P at 7,764.64 — Monday’s 7,764.70 settle held to the tick area — while the Nasdaq added a second straight record at 27,244.28 (+0.5%). The Dow finished soft at 51,863.69 (−0.4%). The Russell closed 2,889.92 (+0.5%). Brent settled $99.25 after briefly trading under $98 in the morning. Path still inherits 3.75%–4.00%.
The public tape was two stories on one board. Reuters: Micron and Sandisk extended the AI/chip bid into another Nasdaq record. The same Muse narrative that ripped Meta Monday flipped into competition fears Tuesday — Amazon blocked the agent from shopping its platform; Schwab, Airbnb, Uber, and Lyft paid the fear tax. Financials led the S&P sector losers. Williams talked short-rate plumbing. The curve and the banks did the talking that mattered for the Dow.
RTH Market Prep was the day clock, not a forecast. Tuesday’s job was to mark what overnight already spent on the new Monday-anchored daily field, respect that the Friday-anchored weekly map was already through +1SD on ES and NQ, and keep sealed SEP path separate from speaker sentences. Cash did not deliver a broad chase day after a spent week band. Flat S&P and soft Dow are the honest read under a second Nasdaq record.
This note does not rewrite Week Ahead, September 21–25. Tuesday’s RTH Market Prep framed the spent weekly +1SD and the speaker card. Monday’s After the Close handed off Nasdaq record / Meta Muse / oil soft. That handoff held on the S&P settle — and Muse bit back on the competition tape.
What cash had to live with
Overnight was inside the new Monday-anchored daily 1SD on ES and NQ — while the Friday-anchored weekly map was already through +1SD. House daily field from morning Prep — anchored to the September 21 settles — put ES daily 1SD at 7,772.53 – 7,894.47 off 7,833.50, and NQ at 30,456.20 – 31,113.30 off 30,784.75. Prep had ES last near 7,840.50 and NQ near 30,769.50 inside daily 1SD, with both already through weekly +1SD on the Friday map. RTY through daily +1SD. YM upper-half daily 1SD. Gold inside daily 1SD. Crude soft below daily and weekly −1SD with quarterly stretch still loud. That was overnight geography. Cash still had to vote through speakers.
Cash voted flat on the S&P — and another Nasdaq record. Associated Press (via WTOP): S&P 7,764.64 (−0.06 / less than 0.1% vs Mon 7,764.70), Dow 51,863.69 (−185.14 / −0.4%), Nasdaq 27,244.28 (+122.18 / +0.5%), Russell 2,889.92 (+14.56 / +0.5%). Green Monday was the prior close that reset the daily field. Flat Tuesday was the cash answer on the S&P. Keep those as two sentences. Reuters: second straight Nasdaq record close; S&P still less than 0.5% below its August 13 record. Week-to-date (AP): S&P +1.5%, Dow +0.4%, Nasdaq +2.7%, Russell +1%.
Do not conflate cash with futures last. Absolute CME settles stay held until a settled board is verified. Cash open-to-close is the equity vote. Futures last is a different sentence.
Speakers stayed plumbing — not a second rate vote. Prep had Williams then Jefferson on the NY Fed Treasury market conference. Reuters: Williams said the Fed’s framework for controlling short-term rates has been effective in supporting financial markets. Collins wrote support for last week’s hike citing inflation risks. Funds range 3.75%–4.00%, 12–0 still printed. CME FedWatch color in the same wrap put roughly a 53% chance of at least 25bp in October — color on the tape, not a desk forecast to invent size off.
Muse flipped from pure bid into competition fear. Reuters: Micron +5%, Sandisk almost +7% kept the chip bid alive. The same Muse reception that fueled Monday’s Meta rip weighed on consumer and fintech names Tuesday — Schwab −6.1%, Airbnb −3%, Uber and Lyft each more than 1%. Amazon blocked Muse from shopping its platform. Write the catalyst and the fear as separate sentences. Do not collapse them into “AI up.”
Banks led the soft tape under a flat S&P. Reuters: financials −1.68% led S&P sector losers; JPMorgan and Wells Fargo both lost more than 3%. Breadth was honest: about as many S&P stocks climbed as fell; nine new highs against sixteen new lows on the S&P, forty-eight highs against one hundred ten lows on the Nasdaq. Heavy volume — 17.9 billion shares versus a 16.3 billion twenty-session average.
Oil soft held — hope still ≠ deal. AP: Brent briefly below $98 in the morning, then trimmed losses and settled $99.25. Reuters: oil choppy near $100 while Trump’s UN remarks kept diplomacy and escalation in the same paragraph. House board (cross-check only): CL last near 89.91 after Monday’s 95.78 anchor — still soft versus Prep’s daily −1SD edge (93.26) with higher-timeframe stretch still loud. Gold stayed inside the Prep daily band on the morning map. 10-year steady near 4.97% on the house board (Reuters ~4.94%).
Vol compressed further on the equity gauge; oil vol firmed. Into the close (house board): VIX 14.21 (Prep 14.62, Mon 14.87), VXN 20.18 (Prep 20.39), GVZ 23.59, OVX 51.89 (Prep 50.31). Equity vol cooled. Oil vol is still not quiet.
Locations — reference only
No new Tuesday Daily/1h stack grades were verified for this close. Treat morning Prep bands and overnight spend notes as geography only — not a chase list after cash already flat-held the S&P settle under a spent weekly +1SD:
- Morning daily field (Mon-anchored): ES 7,772.53–7,894.47 · NQ 30,456.20–31,113.30 · CL 93.26–98.30
- Overnight inside daily 1SD on ES/NQ with weekly through +1SD already spent
- CL stayed soft versus daily/weekly −1SD on the house board — daily cool is not a quarterly reset
Process only: arm at the print. If you are not there, missed = no chase. A second Nasdaq record under a flat S&P is not a makeup invitation to invent size into Asia off a spent weekly band.
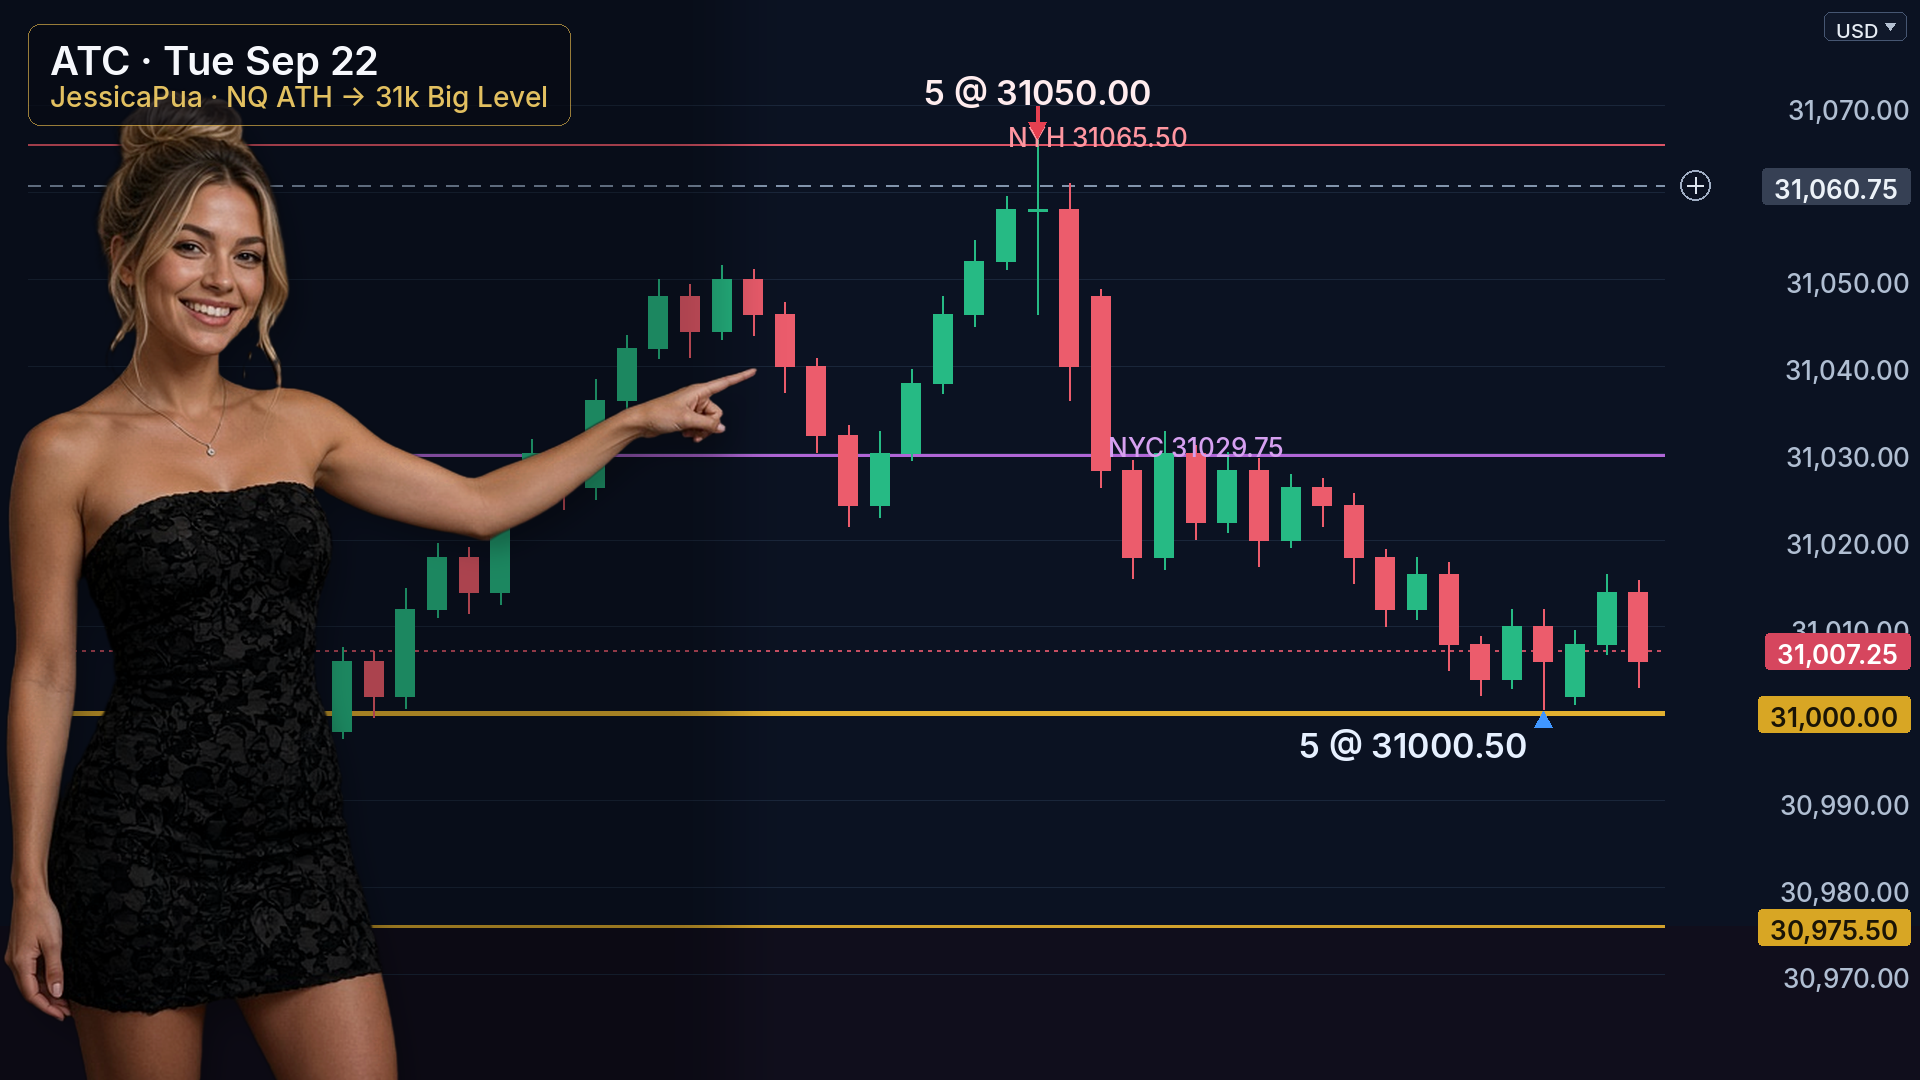
Room gem — JessicaPua presents Michael’s NQ short into 31k
JessicaPua is presenting this desk gem. MichaelPua took the short live in #trader-chat near the NY cash close; Jessica followed his lead into the same trade. Process only — no invented P&L.
Setup on the tape: wait for if NDX or QQQ tagged a new ATH → 2dn with stop at the high → cover into 31k even. (Exact chat does not say “1m 3-bar reversal.”)
Levels on the chart Michael shared (message 1552054272324149300): NYH 31065.50 · short 5 @ 31050.00 · cover 5 @ 31000.50 · Big Level 31000.00.
- “I see that NDX tagged the new ATH just in time to drop it, QQQ almost got there” (~10:07 HT)
- “pretty much! buwahahaha just got out of my short at 31k even” (~10:24 HT)
- “I was just waiting for if ndx or qqq tagged a new ath then all I need was a 2dn with stop at the high” (~10:30 HT)
- “a certain somebody likes to make fun of me for trading yearly levels, but uh, THEY PAY”
- “and we stopped right at 31k even, so randumb!”
#profits-n-lessons was quiet in the window. Thumb uses Jessica’s photo with that room chart — sell near HOD, target into the 31k Big Level.
Asia overnight — what already printed into London
Japan cash stayed dark. Tokyo is closed through Wednesday Sep 23 for Respect for the Aged Day / Silver Week. Nikkei cash resumes Thursday Sep 24. JPX holiday futures can still trade — cash does not. Last Nikkei cash print remains Friday’s 65,018.95.
The rest of Asia was mostly soft-green confirmation, not a rewrite (Yonhap Infomax Asia summary for the 22nd):
- Hang Seng 25,087.75 (+45.04 / +0.18%)
- Hang Seng H-shares 8,362.60 (+0.28%)
- Shanghai Composite 3,952.13 (+2.22 / +0.06%)
- Shenzhen Composite 2,538.64 (−0.01%)
- TAIEX 47,800.17 (+81.33 / +0.17%) — wire flags an all-time high close
Treat Asia as a quiet handoff after Monday’s AI/oil story — not a fresh Tier-1 thesis. Alibaba AI-chip color into a U.S.–China meeting later in the week stays calendar context, not a printed deal.
London watch — what can move the handoff
London closed soft on the FTSE while the Continent held flat-to-firm. FTSE 100 finished 10,708.33 (−30.68 / −0.29%). DAX essentially flat near 25,578.85 on the house board. AP’s midday color already had London as the outlier dip while much of Europe and Asia ticked higher.
London into Wednesday inherits a flat U.S. S&P settle, a second Nasdaq record, soft banks, soft oil, and the first live September activity print after the hike:
| Time (ET) | Item | Why it matters for London → NY |
|---|---|---|
| Wed ~9:45 a.m. | S&P Global Flash Manufacturing + Services PMI (September) | First live September activity read after the Sep 16 hike |
| Wed ~10:05 a.m. | Governor Barr on housing | Board voice — process and housing color, not a second SEP |
| Thu | U.S.–China leaders meeting on the card | AI / trade truce color (Reuters) — hope ≠ printed framework |
Also still live: path inherits 3.75%–4.00%. Flat Tuesday and firm Asia do not reopen the ballot. Flash PMI is the next clock that can move the week’s activity read — size against invalidation, not against the headline.
What Asia and London inherit
Overnight does not reset the week. It inherits six open facts:
- Monday’s S&P settle held. AP S&P 7,764.64 after Monday’s 7,764.70 — flat hold near the record, not a broad chase after weekly through +1SD was already spent.
- Nasdaq printed a second straight record at 27,244.28 while the Dow finished soft and financials led losers — leadership stayed narrow.
- Muse bit back. Chip bid continued; competition fears hit Schwab, Airbnb, and the ride-hails. Catalyst and fear stay separate sentences.
- The vote stays printed. Funds range 3.75%–4.00%, 12–0. Speakers talked plumbing. October FedWatch odds are color, not a size ticket.
- Oil soft held. Brent settle $99.25 after a sub-$98 morning print. Hope ≠ deal. Daily/weekly cool is not a higher-timeframe reset.
- Japan cash holiday through Wednesday. Asia ex-Japan mostly soft green. London inherits flat S&P geography plus Wednesday flash PMI — not a blank Tuesday rewrite.
Use the September 21-anchored daily field from Tuesday’s RTH Market Prep as overnight geography until a new verified map is on the card. Write size and invalidation before the next impulse — not after.
Daily Expected-Move Map
Verified from the house expected-moves publisher off the 2026-09-21 close — Tuesday RTH Market Prep table only. Not a forecast. Overnight + cash already spent part of this field — especially inside-daily ES/NQ with weekly through +1SD already spent, flat S&P cash hold, second Nasdaq record, and CL soft versus daily/weekly −1SD. Do not invent new bands from Tuesday’s close.
| Contract | Anchor Close | Daily 1SD | Daily 2SD | Spend note |
|---|---|---|---|---|
| ES | 7,833.50 | 7,772.53 – 7,894.47 (±60.97) | 7,711.56 – 7,955.44 | Overnight inside 1SD; weekly through +1SD; cash S&P 7,764.64 flat vs Mon — do not conflate cash with futures last |
| NQ | 30,784.75 | 30,456.20 – 31,113.30 (±328.55) | 30,127.64 – 31,441.86 | Overnight inside 1SD; weekly through +1SD; cash Nasdaq 27,244.28 second record |
| YM | 52,475 | 52,067 – 52,883 (±408) | 51,658 – 53,292 | Prep overnight upper-half 1SD; cash Dow soft |
| RTY | 2,897.40 | 2,874.85 – 2,919.95 (±22.55) | 2,852.30 – 2,942.50 | Prep overnight through +1SD; cash Russell 2,889.92 |
| GC | 4,383.90 | 4,330.25 – 4,437.55 (±53.65) | 4,276.60 – 4,491.20 | Prep overnight inside 1SD |
| CL | 95.78 | 93.26 – 98.30 (±2.52) | 90.74 – 100.82 | Soft vs daily −1SD + weekly −1SD (house last ~89.91). Brent settle $99.25 (AP). Quarterly stretch still loud |
Vol snapshot (house close cross-check): VIX 14.21 | VXN 20.18 | GVZ 23.59 | OVX 51.89. Equity vol compressed further; oil vol firmed versus Prep. Respect acceptance outside the band; do not invent a chase from a second Nasdaq record alone.
Build your free Survive First risk plan
Educational content only. Futures involve substantial risk of loss and are not suitable for all investors. This is not financial advice.
Sources
- How major US stock indexes fared Tuesday 9/22/2026 — AP via WTOP
- Nasdaq reaches record high close, AI stocks rally — Reuters
- Asian Stock Markets Summary — Yonhap Infomax
- Federal Reserve Board — September 2026 calendar
- NY Fed — 2026 U.S. Treasury Market Conference
- Week Ahead September 21–25
- RTH Market Prep September 22
- After the Close September 21
Related Articles
Rates Busy. Soft JOLTS. Oil Cooled. Gold Late Bear.
Prep framed Mon red cash, gold soft, and Tuesday JOLTS into PCE/NFP bookends. Soft JOLTS printed 7.079M. Cash slight red. Rates busy — AP 10Y 5.25%. Oil cooled — Brent $96.16; Spotter CL 90.07. Gold late bear 4194.5. Separate the clocks.
Ladder Still Working. Cash Went Red. Gold Soft.
Prep framed overnight oil spike, gold soft under expected-move lows, equities inside the daily expected move into a light Monday. Cash closed red. Spotter oil still working 94.68/92.78 — separate oil from red cash from soft gold.
Ladder Left Behind. Cash Went Green. Michigan Soft.
Prep asked oil continuation only at the overnight ladder. Cash printed lower on the CL tickets while equities closed green into the weekend. Final Michigan soft at 48.1 — separate the oil miss from the green cash.