After the Close Sept. 14: The Easy Band Was Overnight. Cash Soft. Wednesday Sealed.
Overnight NQ through daily −1SD off Fri 29,387. Cash indexes closed soft vs Friday’s green relief after an early AI/risk-off open and afternoon clawback. CL tempered off overnight highs. Empire Tue; FOMC Wed.
Monday, September 14, 2026
Quiet Monday on the agency calendars. Overnight already spent Nasdaq’s easy daily −1SD off Friday’s 29,387 settle. Cash indexes closed soft versus Friday’s green relief after an early risk-off open and an afternoon clawback. Crude tempered off overnight highs into a lower-level late-cash spend. Empire prints Tuesday. The rate decision still owns Wednesday.
Morning Pulse was the day clock, not a forecast. Monday’s job was to mark what Globex already used, write size against what was left, and leave Wednesday’s statement on Wednesday’s card. Cash answered the Pulse question: post-CPI repair did not hold as a green follow-through. It voted soft — and still did not authorize inventing FOMC size today.
This note does not rewrite Week Ahead, September 14–18. Monday’s Pulse had the overnight spend and the map already on the board. Friday’s After the Close locked the twin flip and the green-day / red-week split. That handoff still holds into Empire and the vote.
What cash had to live with
Overnight already spent the easy Nasdaq side. House daily map — anchored to the September 11 close — put NQ daily 1SD at 28,826.98 – 29,947.02 off 29,387.00. Pulse had the overnight low near 28,816 — through daily −1SD — with last still soft into the Hawaii window. ES stayed inside 1SD (7,549.51 – 7,769.49 off 7,659.50). Do not treat an NQ −1SD tag as if every index already spent the same side.
Cash opened into that spent geography and sold the leadership first. Spotter 1h into the open (~3:30–3:50 a.m. HT): NQ bearish 29,040.75 · YM 52,443 · RTY 2,901.6. Mid-cash added ES bearish 7,629 (~5:38 a.m. HT). Near the close the tape clawed: NQ bullish 29,208.5 into the resting NQ Daily 29,213 neighborhood, with ES bullish 7,627 and ZN bullish 106.015625. Cash never printed a new equity Daily — resting equity Dailies (ES 7,672.25 · NQ 29,213 · ZN d1 106.65625 · HG 6.7025) stayed reference only. DXY Daily 99.436 (99.392–99.436) held as the live Daily into cash from the Sunday/early-Monday London handoff. ZN weekly 106.6875 stayed the held weekly from Sunday Globex reopen.
Equities closed soft versus Friday. Cash indexes (AP wire): S&P 7,619.98 (−37.00), Dow 52,421.20 (−152.09), Nasdaq 26,186.41 (−146.62). Friday’s cash session closed green open-to-close (ABC: S&P 7,656.98 +0.9%, Dow 52,573.29 +1%, Nasdaq 26,333.04 +1%). Those are two sentences. Monday did not rewrite Friday’s green relief into a week acceptance — and it did not invent a new overnight thesis for Wednesday.
Crude reclaimed overnight, then tempered. Pulse had CL inside daily 1SD (94.71 – 105.39 off Friday’s 100.05) testing the upper half (~104.25 / H ~104.95). Spotter overnight carried bearish prints at 102.07 / 102.75 and London-side 103.62; late cash spent bullish 100.78 / 100.66 after those high prints. AP had Brent near $105.68 after a morning push that cooled midday. Cooling from an overnight stretch is not a higher-timeframe reset — monthly +1SD / quarterly +2SD stretch on the Pulse map stays loud. Absolute futures settles stay held until a CME board is on the desk.
Locations that printed — and the ones that didn’t
Process only: arm at the print. If you are not there, missed = no chase.
- Held Daily into cash: DXY 99.436. No new cash equity Daily.
- Open risk-off 1h: NQ 29,040.75 · YM 52,443 · RTY 2,901.6.
- Mid cash: ES 7,629.
- Near-close reclaim: NQ 29,208.5 (into Daily 29,213 neighborhood) · ES 7,627 · ZN 106.015625.
- CL path: overnight highs 102.07 / 102.75 / 103.62 → late-cash bullish 100.78 / 100.66.
- Resting reference (not re-tapped cash): ES Daily 7,672.25 · NQ Daily 29,213 · ZN d1 106.65625 · HG 6.7025 · ZN w1 106.6875.
Older resting locations stay if price returns. They are not a makeup card after the overnight −1SD and the open risk-off already printed.
Desk color: confirmation, median, messy middle
The room left usable Monday management without needing unread screenshots.
Mike walked a fade example off a minor 1-minute reversal — 212, retrace-fill the imbalance after tagging the hourly UW, inside the huli huli window, aiming for the RTH midpoint — and said there is no guarantee it works. The useful line was the risk math: the more confirmation you need, the more risk you must also have. Enter at the level, or on a sweep-close that respects it, or when the 212 becomes true, or on the imbalance fill — favorite path is to add across those concepts and take profit at the big level below. He flagged the hourly candle close above 29,000: it does not have to hold, but ignoring that and not managing risk properly is how green trades turn red. He stepped out for poke bowls when the resistance above did not look convincing against a large gap down and higher-probability targets further up.
Later he drilled the CDM / CDO drum. When price is coming from the highs or the lows, the median becomes liquidity — a strong candidate for reversal location. A CDM short is valid if price actually reaches it; if price does not make a new low and then revisits the CDM, that revisit can fail to reverse. CDO is similar: first return from the highs or lows is a strong reversal candidate, especially when it sits further than the CDM was. Drill the logic; combine it with your own strategy; do not invent levels from screenshots.
Into the afternoon he left the identity line clean: if you trade Pono you are a data and probabilities trader first — level trader least risk, pattern trader more, multi-confirmation trader the most. Keep the key data points so you know when the easy money and the high-probability events have already printed. Daily ATR had an extremely high chance of reaching 80% and was then at 67%, price stuck in the messy middle without a catalyst — so he left the stare for Honoliʻi rather than invent size into a coasting tape.
What Asia and London inherit
Overnight does not reset the week. It inherits six open facts:
- NQ already used the easy daily −1SD before cash. Leftover field toward −2SD is thinner. Cash sold the open, then clawed toward the resting Daily 29,213 neighborhood via 1h 29,208.5 — spent geography, not a fresh chase card.
- Cash closed soft versus Friday’s green relief. Friday closed green open-to-close. Monday closed red on the AP index prints after an early AI/risk-off sleeve and an afternoon repair. Two sentences. Keep them separate.
- CL stretched the upper half overnight and tempered into late-cash lower-level bullish prints. Daily band still open. Higher-timeframe stretch still loud. Do not treat tempering as a blank card.
- DXY Daily printed and held into cash; equity Dailies did not reprint. Dollar location traveled. Equity Daily resting stays reference until price returns.
- Desk management traveled: confirmation costs risk; hourly close above 29,000 is a manage-risk sentence; CDM/CDO from highs/lows; messy-middle ATR is a leave-the-stare cue — not an invitation to invent Wednesday size.
- Empire Tuesday. FOMC Wednesday. Retail and trade prices Wednesday morning are context for the afternoon statement — not a separate max-size invitation before 2:00 p.m. ET.
Use the September 11-anchored daily field from Monday Pulse as overnight geography until a new verified map is on the card. Write size and invalidation before the next impulse — not after.
Daily Expected-Move Map
Verified from the house expected-moves publisher off the 2026-09-11 close — Monday Pulse table only. Not a forecast. Overnight + cash already spent part of this field — especially NQ through −1SD overnight and open risk-off into a near-close reclaim toward resting Daily geography. Do not invent new bands from Monday’s close.
| Contract | Anchor Close | Daily 1SD | Daily 2SD | Spend note |
|---|---|---|---|---|
| ES | 7,659.50 | 7,549.51 – 7,769.49 (±109.99) | 7,439.51 – 7,879.49 | Inside 1SD overnight; mid-cash bearish 7,629; near-close bullish 7,627 |
| NQ | 29,387.00 | 28,826.98 – 29,947.02 (±560.02) | 28,266.96 – 30,507.04 | Through −1SD overnight; open bearish 29,040.75; near-close bullish 29,208.5 → Daily 29,213 neighborhood |
| YM | 52,585 | 51,830 – 53,340 (±755) | 51,075 – 54,095 | Inside 1SD; open bearish 52,443 |
| RTY | 2,904.50 | 2,862.79 – 2,946.21 (±41.71) | 2,821.08 – 2,987.92 | Inside 1SD; open bearish 2,901.6 |
| GC | 4,366.20 | 4,264.55 – 4,467.85 (±101.65) | 4,162.90 – 4,569.50 | Inside 1SD (Pulse) |
| CL | 100.05 | 94.71 – 105.39 (±5.34) | 89.36 – 110.74 | Overnight upper half → late-cash bullish 100.78 / 100.66; HTF stretch still loud |
Weekly (anchored 2026-09-11): NQ 1SD 28,531.56 – 30,242.44. ES 1SD 7,491.48 – 7,827.52. CL weekly 1SD 91.89 – 108.21.
Vol snapshot at EM run: VIX 17.73% | VXN 21.02% | GVZ 25.68% | OVX 58.92%. Oil vol is not compressed. Acceptance outside the remaining band matters more than noise inside what is left.
What this close does not do
It does not invent absolute futures settles. Cash indexes closed soft on the AP wire. Futures points stay held until settled.
It does not invent a fresh expected-move field from the close. Pulse Sep 14 bands — already partly spent overnight — are the map into Empire.
It does not chase a spent Nasdaq overnight band. Daily −1SD was used before cash. Open risk-off and near-close reclaim are interactions with a spent field — not a second invitation to invent size after the tag.
It does not turn Friday’s green relief into Monday acceptance. Friday closed green open-to-close. Monday closed soft versus that prior close. Relief and follow-through are different sentences.
It does not spend Wednesday’s FOMC. Empire Tuesday is positioning. Retail and trade prices Wednesday morning are context. Statement first. Paths second. A quiet Monday leftover does not authorize sizing the vote today.
Steal this / leave that
Steal this: Mark NQ’s overnight −1SD spend before treating any Monday leftover as fresh. Respect the open risk-off prints and the near-close reclaim into 29,213 only if you are still at the print. Treat CL’s overnight stretch → late-cash 100.78 / 100.66 as tempering inside an open daily band, not a HTF reset. Manage risk when an hourly close prints above 29,000. Keep CDM/CDO logic when price comes from the highs or lows. Leave the messy middle when Daily ATR is mid-range without a catalyst. Keep FOMC size on Wednesday’s card. Missed = no chase.
Leave that: Chasing Nasdaq lower after overnight −1SD as if the field were fresh. Treating Friday’s green cash session as week acceptance. Inventing futures settles or new EM bands to force a louder sentence. Spending Wednesday’s rate decision on a quiet Monday leftover. Staring through a 67% ATR messy middle because one high-probability event has not printed yet.
Monday was the map. Cash voted soft. Overnight already used the easy Nasdaq side. What is left is Empire Tuesday — and Wednesday’s vote.
Build your free Survive First risk plan
Location, size, invalidation, and the condition that kills the idea.
Futures involve substantial risk. Educational content only; this is not financial advice.
Sources
- PonoTrading Market Pulse, September 14, 2026
- PonoTrading Week Ahead, September 14–18, 2026
- PonoTrading After the Close, September 11, 2026
- House expected-moves publisher dry-run for trade date 2026-09-14 (anchor 2026-09-11 close) — Pulse table only
- Federal Reserve — FOMC calendars
- AP market close reprint (Stan Choe) — S&P 7,619.98 / Dow 52,421.20 / Nasdaq 26,186.41; Brent ~$105.68 after morning spike
- Spotter Mon Sep 14 location stack (desk) — prints only
- Discord trader-chat michaelpua gems 2026-09-14 (~03:57–05:04 HT) — exact quotes only; #profits-n-lessons empty
Related Articles
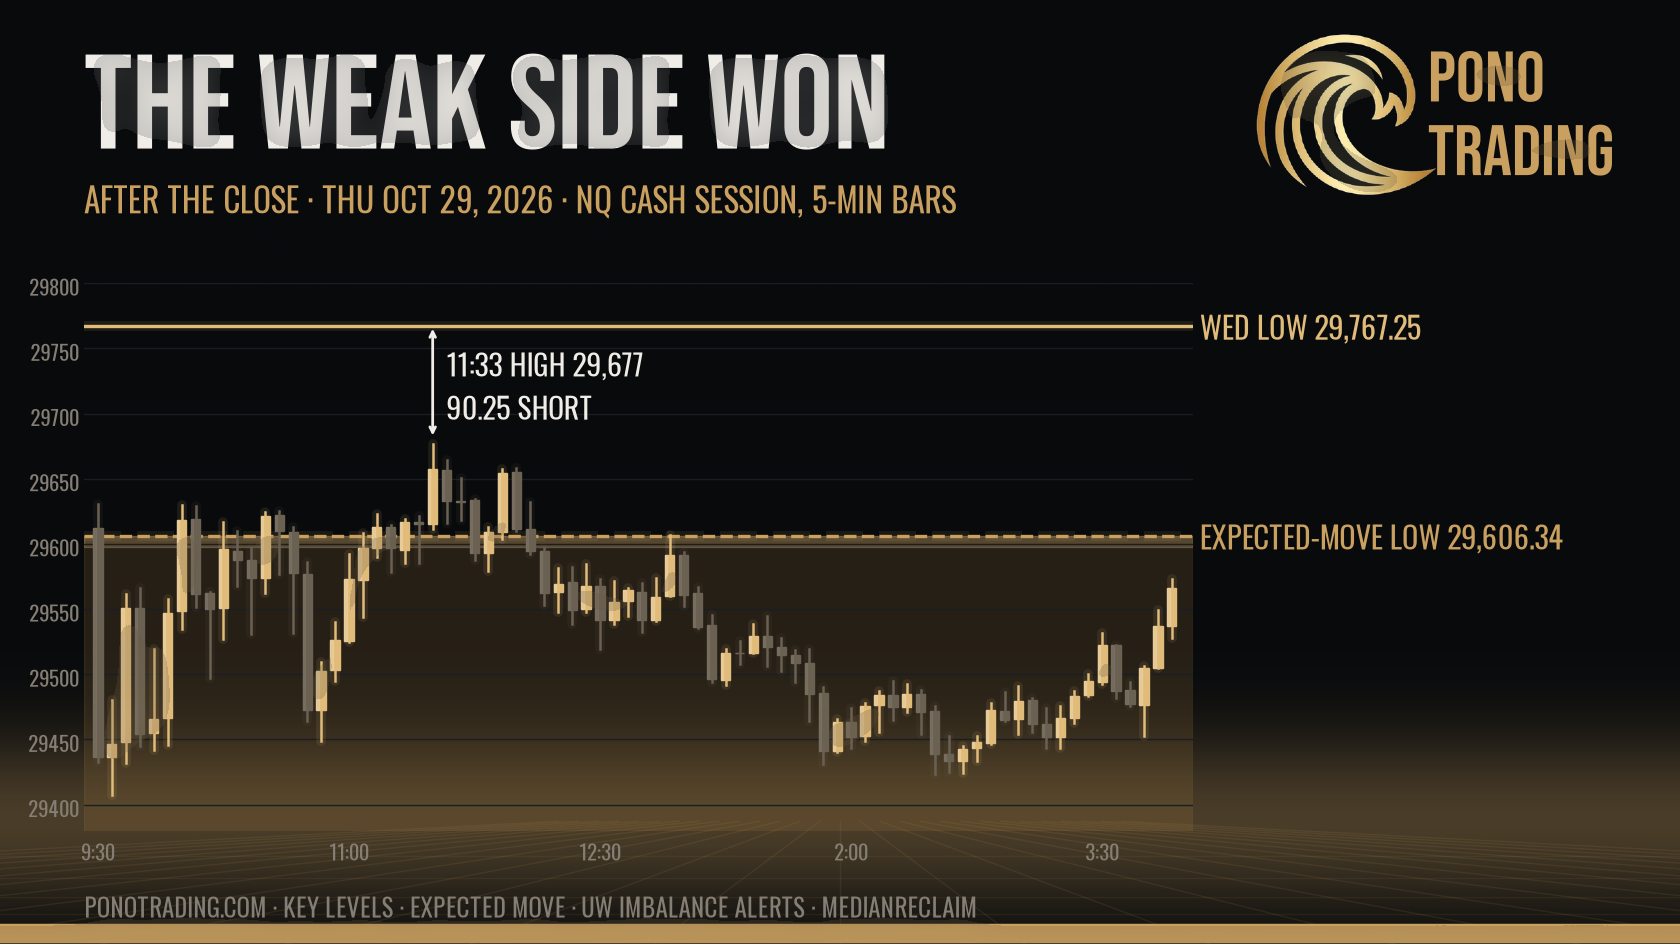
The Weak Side Won
NQ never got back to Wednesday's low and finished under its daily expected move, ES gave up its reclaim at the open, RTY went the other way. Scoring the morning call and the alerts.
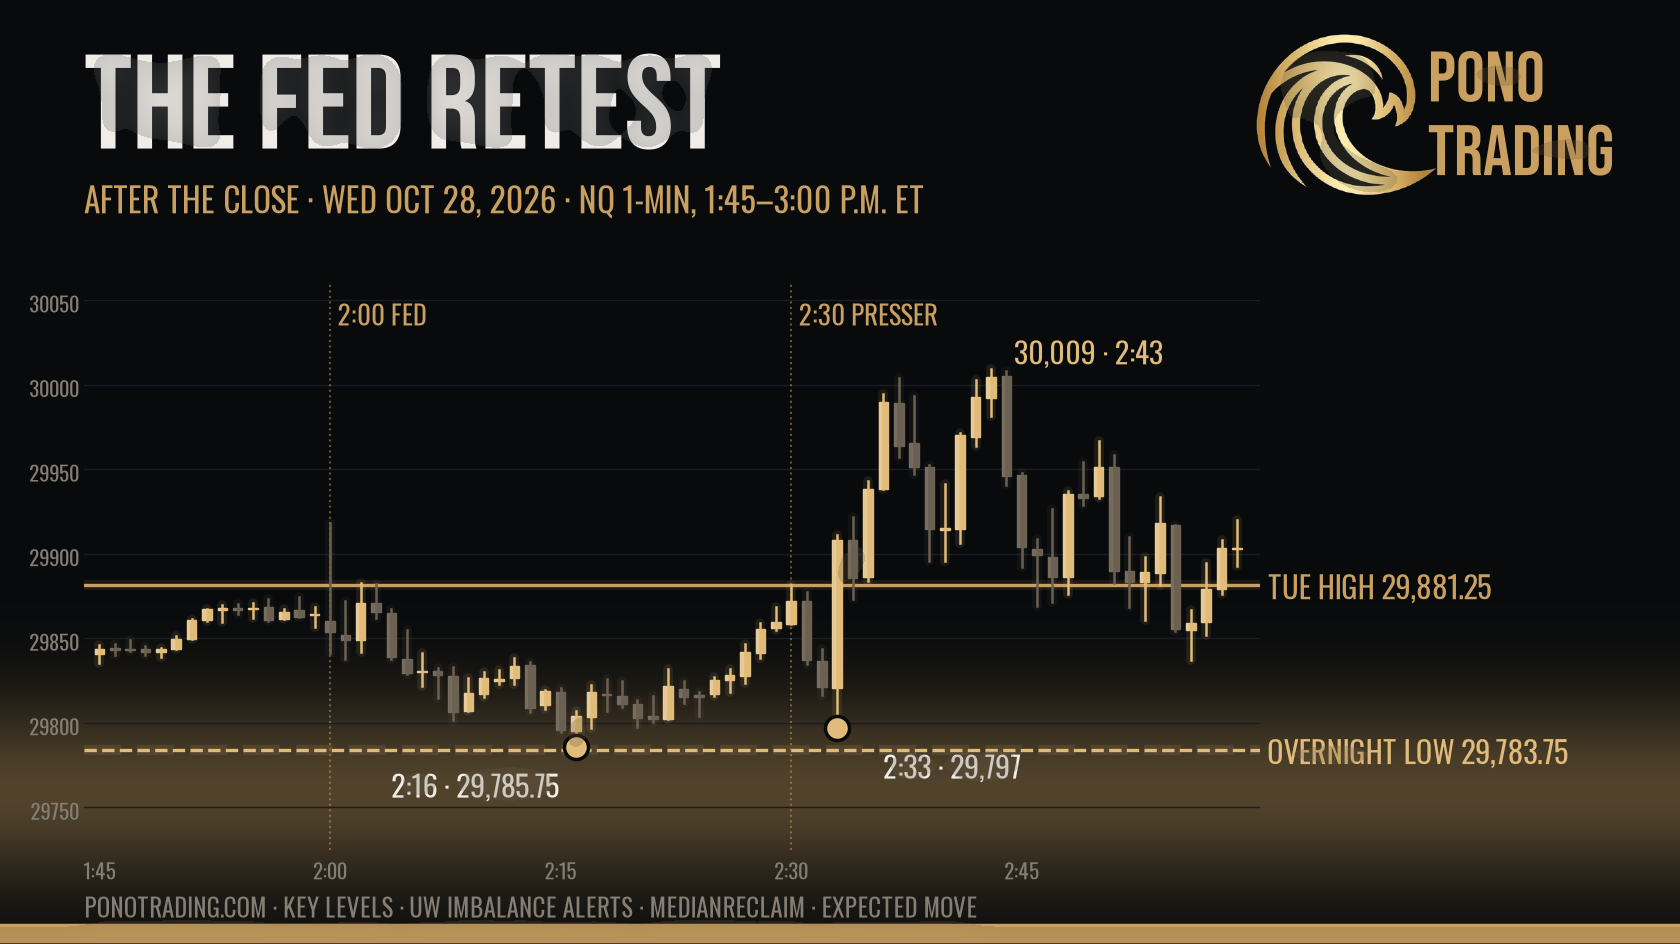
The Fed Retest
NQ lost Tuesday's high at 9:41 a.m., then the Fed pushed it back to the overnight low twice and the line held both times. Scoring the morning call, the alerts and the Fed window.
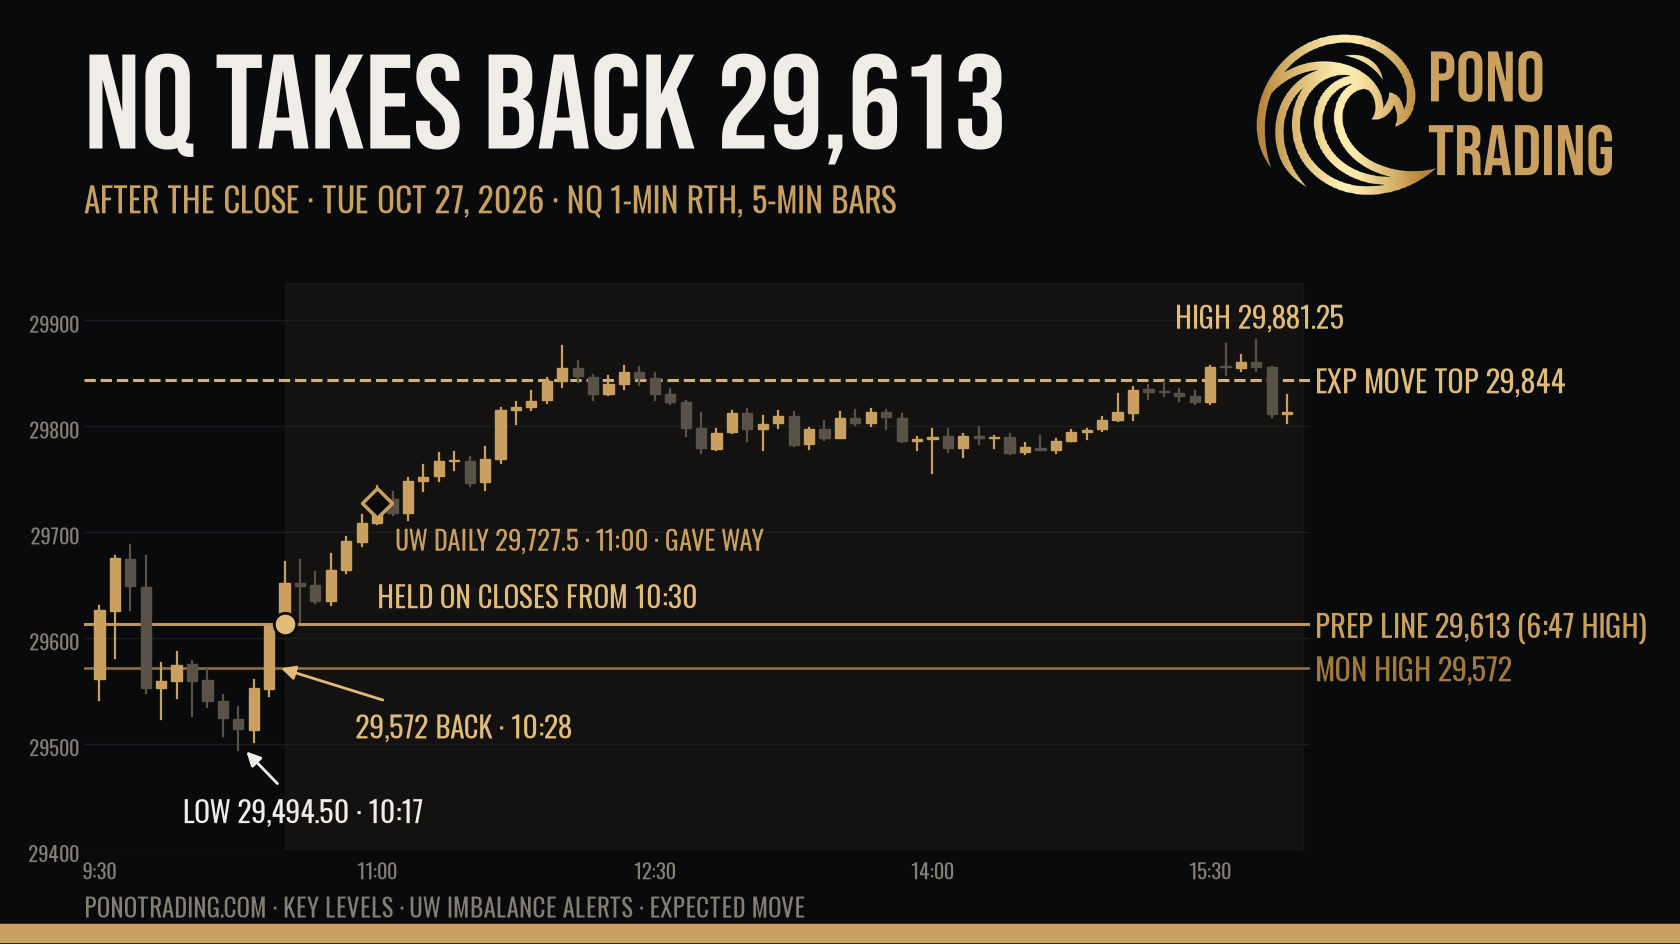
The Putback
NQ rimmed out at Monday's high overnight, then took 29,613 back for good at 10:30 a.m. and ran to the top of its expected move. The morning call was wrong; here is how.