The Repair Failed in Large Caps, but Small Caps Refused the Risk-Off Script
Large-cap repair failed, but small caps stayed positive and volatility eased while crude reclaimed its anchor ahead of CPI.
Tuesday, August 11, 2026
The morning repair did not survive the close in large-cap equities. The more useful message, however, was not simply that stocks fell. It was that crude rebounded, volatility eased, and small caps stayed positive while the S&P 500, Nasdaq, and Dow finished lower.
That is a divided tape, not a clean risk-off verdict.
The S&P 500 closed at 7,728.20, down 0.32% from Monday. The Nasdaq Composite finished at 26,445.45, down 0.60%, while the Dow closed at 53,791.85, down 0.34%. The Russell 2000 was the exception, ending at 3,027.12, up 0.32%.
What Changed After the Morning Plan
The morning Market Pulse identified three possible paths: confirmed equity repair, a failed crude rejection, or pre-CPI compression. The session delivered pieces of all three, but none in its cleanest form.
- Large-cap repair failed. ES and NQ lost their morning futures anchors instead of accepting toward daily +1SD.
- Crude's overnight rejection did not hold. WTI recovered from a regular-session low near 81.27 to roughly 83.47 late in the session, back above the 82.13 anchor but still below the 84.22-84.54 upper decision zone.
- Small caps held up. Russell 2000 finished positive even as the Nasdaq Composite lagged.
- Volatility did not confirm panic. Delayed observations showed VIX near 15.31, VXN near 22.37, OVX near 54.84, and GVZ near 26.07, all below Monday's references.
- Rates and the dollar stayed contained. The delayed 10-year yield reference was near 4.684%, while DXY was effectively unchanged near 99.81.
The session therefore rejected the easy bullish interpretation without producing a broad liquidation signal.
Closing Dashboard
| Market | Closing / late-session observation | Change vs. prior reference | Read |
|---|---|---|---|
| S&P 500 | 7,728.20 | -0.32% | Morning repair failed |
| Nasdaq Composite | 26,445.45 | -0.60% | Large-cap growth lagged |
| Dow | 53,791.85 | -0.34% | Closed near session lows |
| Russell 2000 | 3,027.12 | +0.32% | Positive divergence |
| ES futures | 7,746.00 | -0.40% | Below 7,776.75 anchor |
| NQ futures | 29,614.25 | -0.41% | Below 29,737 anchor |
| WTI crude | 83.47 | +1.63% | Reclaimed anchor; below upper field |
| Gold | 4,429.10 | +0.21% | Just above daily +1SD 4,425.50 |
| 10-year yield | 4.684% | -1.5 bp | No rate-shock confirmation |
| DXY | 99.81 | Flat | No dollar confirmation |
Cash-index closes are the official 4:00 p.m. ET observations. Futures, volatility products, rates, dollar, crude, and gold are delayed late-session references rather than official settlements.
Leadership Was the Real Story
The Nasdaq Composite underperformed while the Russell 2000 finished green. That matters because the morning setup began with NQ as the strongest repair candidate and RTY as the laggard. By the close, that relationship had reversed.
This is not enough to declare a durable rotation into small caps. One session before CPI, it is better treated as evidence that the tape was reallocating risk rather than abandoning it wholesale. The confirmation test comes next: Russell strength needs to persist without a fresh jump in yields, while Nasdaq needs to recover its lost anchor before traders call today's weakness a simple dip.
Crude Reclaimed the Anchor, Not the Breakout
WTI's morning rejection from 84.61 initially supported the repair thesis. During the regular session, crude reversed again—from roughly 81.27 to about 83.47—and reclaimed its 82.13 anchor.
The distinction is important. Crude restored pressure, but it did not regain the 84.22 weekly +1SD to 84.54 daily +1SD decision zone. Calling that a breakout would be hindsight. Calling it irrelevant would ignore the day's strongest cross-asset reversal.
For Wednesday, a hold above 82.13 keeps the upper field in play. A failure back below that anchor would turn today's rebound into another rejected auction.
The EIA's August Short-Term Energy Outlook reinforced why that pivot matters. The agency now assumes severe Strait of Hormuz transit constraints persist through August and forecasts Brent near $85 per barrel in the third quarter. That is a macro backdrop, not an intraday trigger, but it keeps oil from becoming a one-session footnote ahead of CPI.
Volatility Refused to Confirm the Index Weakness
Broad equity volatility and the market-specific volatility gauges all eased in the delayed closing window. VIX and VXN fell even as the S&P 500 and Nasdaq closed lower; OVX eased despite crude's rebound; GVZ declined while gold held just beyond daily +1SD.
That does not make the index decline bullish. It says the close lacked the kind of protection demand that normally strengthens a high-conviction risk-off interpretation. With CPI due Wednesday at 8:30 a.m. ET, traders may have reduced directional exposure without aggressively bidding volatility into the bell.
What Held, Failed, and Surprised
Held
- Crude remained below the upper 84.22-84.54 expansion zone.
- Rates and the dollar stayed contained.
- Gold held just above daily +1SD without reaching weekly +1SD.
Failed
- ES did not hold 7,776.75.
- NQ did not hold 29,737.
- The morning's NQ-led repair never earned cash-session acceptance.
Surprised
- Russell 2000 finished positive while all three large-cap cash indexes closed lower.
- Volatility gauges eased instead of confirming the late index weakness.
- Crude reclaimed its anchor after the morning note highlighted its overnight rejection.
Asia and London Preparation
Asia inherits a split close: weaker U.S. large-cap indexes, firmer small caps, rebounding crude, steady rates, and subdued volatility. That combination favors confirmation over prediction.
For equity bulls, the first repair signal is ES reclaiming 7,776.75 and NQ reclaiming 29,737, ideally while crude remains below 84.22-84.54. Without those reclaims, Tuesday's failed repair remains the active structure.
For equity bears, the better continuation signal is not simply a red overnight candle. It is acceptance below Tuesday's cash lows—about 7,717 in the S&P 500 and 26,372 in the Nasdaq Composite—paired with VIX or VXN finally expanding.
For crude traders, 82.13 is the renewed pivot. Holding above it keeps the upper expected-move field in play. Losing it would weaken the inflation-pressure narrative again.
For gold traders, 4,425.50 remains the immediate decision level. Holding above it preserves the daily expansion; falling back inside the field would reduce the strength of the hedge signal before CPI.
London should be especially careful with moves that occur before the U.S. inflation release. Wednesday CPI can invalidate an otherwise clean overnight structure at 8:30 a.m. ET.
The Lesson: Do Not Force One Label onto a Divided Tape
The morning plan was useful because it defined what confirmation required. When NQ and ES lost their anchors, the bullish repair thesis failed. But small-cap strength and falling volatility also prevented a clean risk-off confirmation.
That is why scenario trading is more durable than headline trading. A failed bullish scenario does not automatically validate the strongest bearish scenario. Sometimes the correct update is narrower: large-cap repair failed, cross-asset pressure returned, and the market still withheld broad confirmation.
Put Tomorrow's Decision Map on Your Screen
Use expected-move boundaries as decision zones, then require acceptance and cross-asset confirmation before committing risk.
Open the PonoTrading Expected Move Tracker
Bottom Line
Tuesday closed with weaker large caps, stronger small caps, firmer crude, steady rates, and softer volatility. The morning repair failed in ES and NQ, but the tape did not confirm a broad flight from risk.
Asia and London inherit a market that still needs proof. Reclaims of 7,776.75 ES and 29,737 NQ would restart repair. Acceptance below Tuesday's cash lows with expanding volatility would strengthen downside continuation. Between those signals—and one CPI print away—discipline matters more than a confident label.
Cash-index data reflects the August 11, 2026 official 4:00 p.m. ET close. Other market values are delayed observations and not executable quotes or official settlements. Expected-move levels are model-derived estimates, not guarantees. Educational content only; futures involve substantial risk and this is not financial advice.
Sources
- Associated Press: How major U.S. stock indexes fared Tuesday
- Associated Press: U.S. stocks slip as oil prices keep swinging
- U.S. Bureau of Labor Statistics: August 2026 release calendar
- U.S. Energy Information Administration: August Short-Term Energy Outlook
- Yahoo Finance delayed five-minute chart data captured after the cash close
Related Articles
NQ Traded Under Its Expected-Move Low, Then Settled In Discount
NQ opened in premium over its PDM at 28,348.375, traded down to 27,695.25, 265 points under its expected-move low, and settled in discount at 28,034.75.
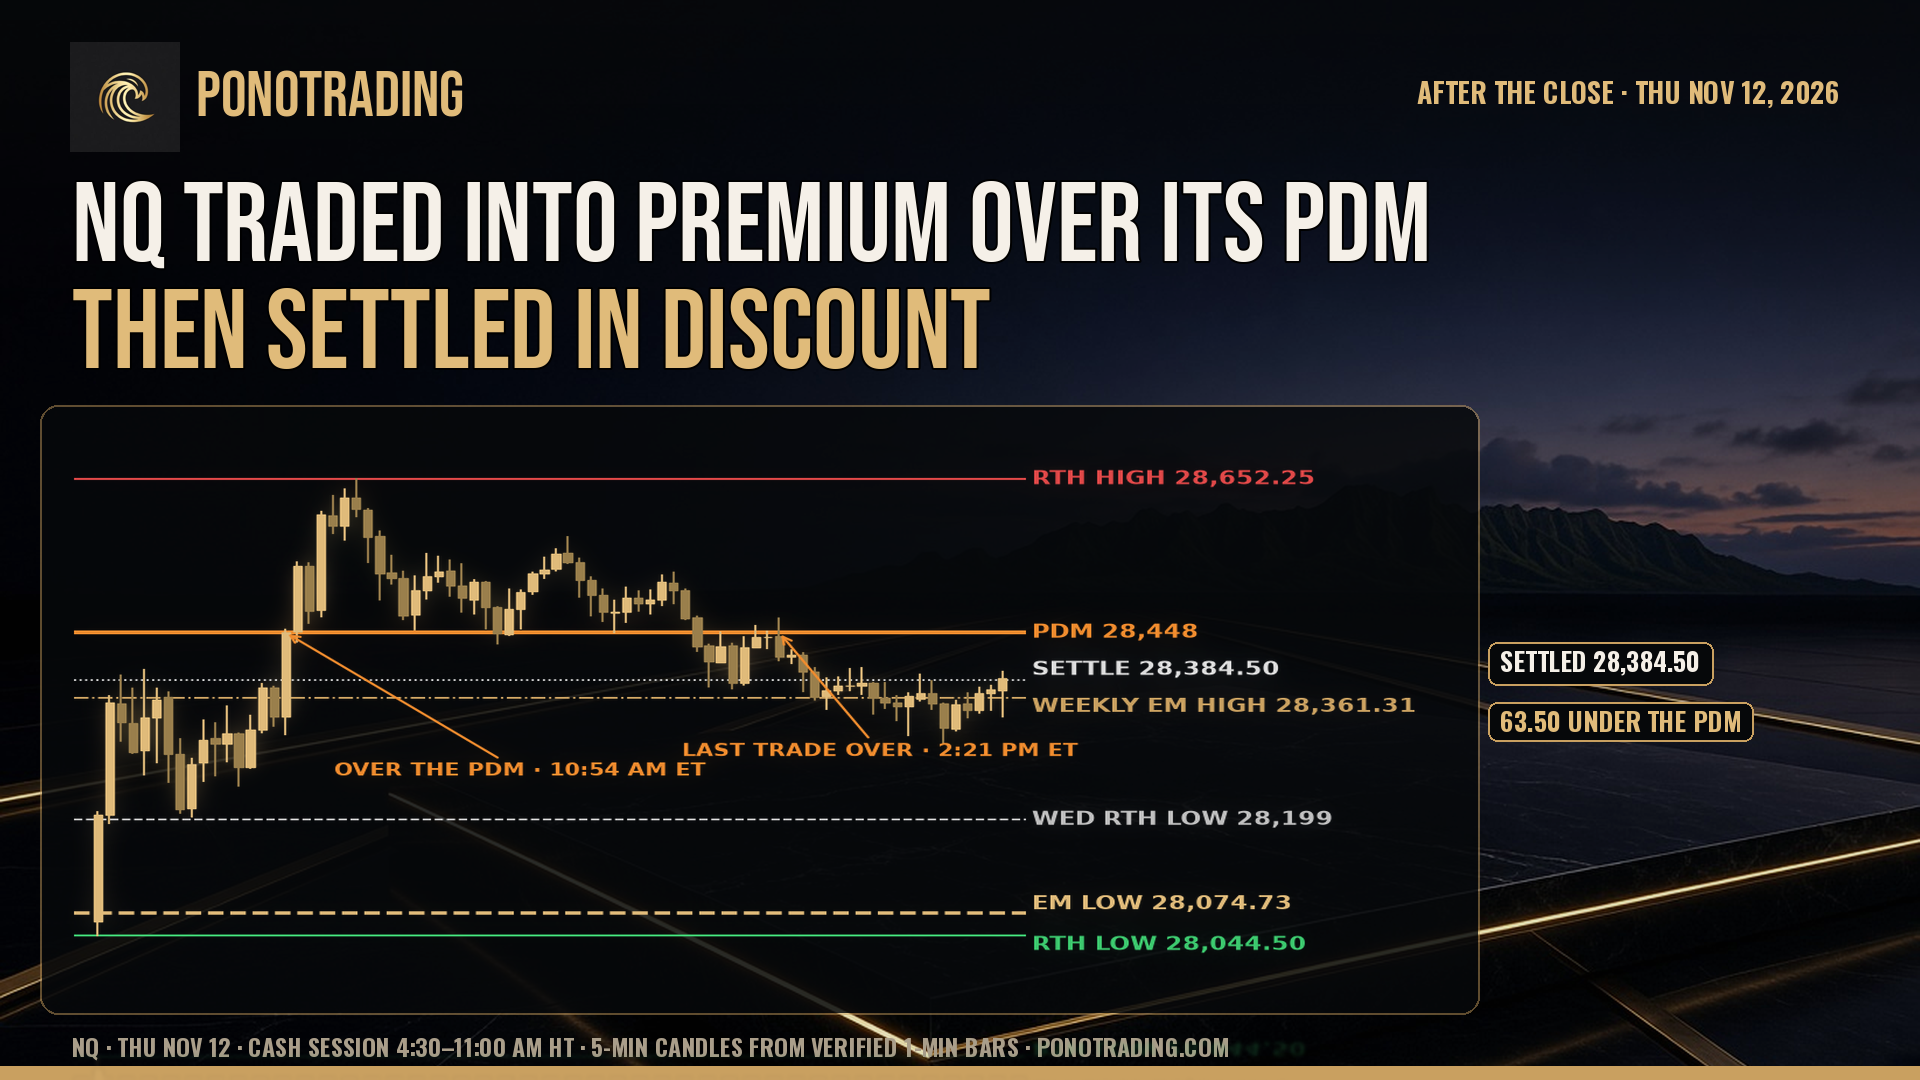
NQ Traded Into Premium Over Its PDM, Then Settled In Discount
NQ opened under its expected-move low, took back Wednesday's RTH low at 28,199 and traded into premium over its PDM at 28,448, then settled in discount under it. ES traded above Wednesday's RTH high in the 11:19–11:24 ET window. The morning prep next to what price did, the alert board, Friday's PDM and the plan into PPI.
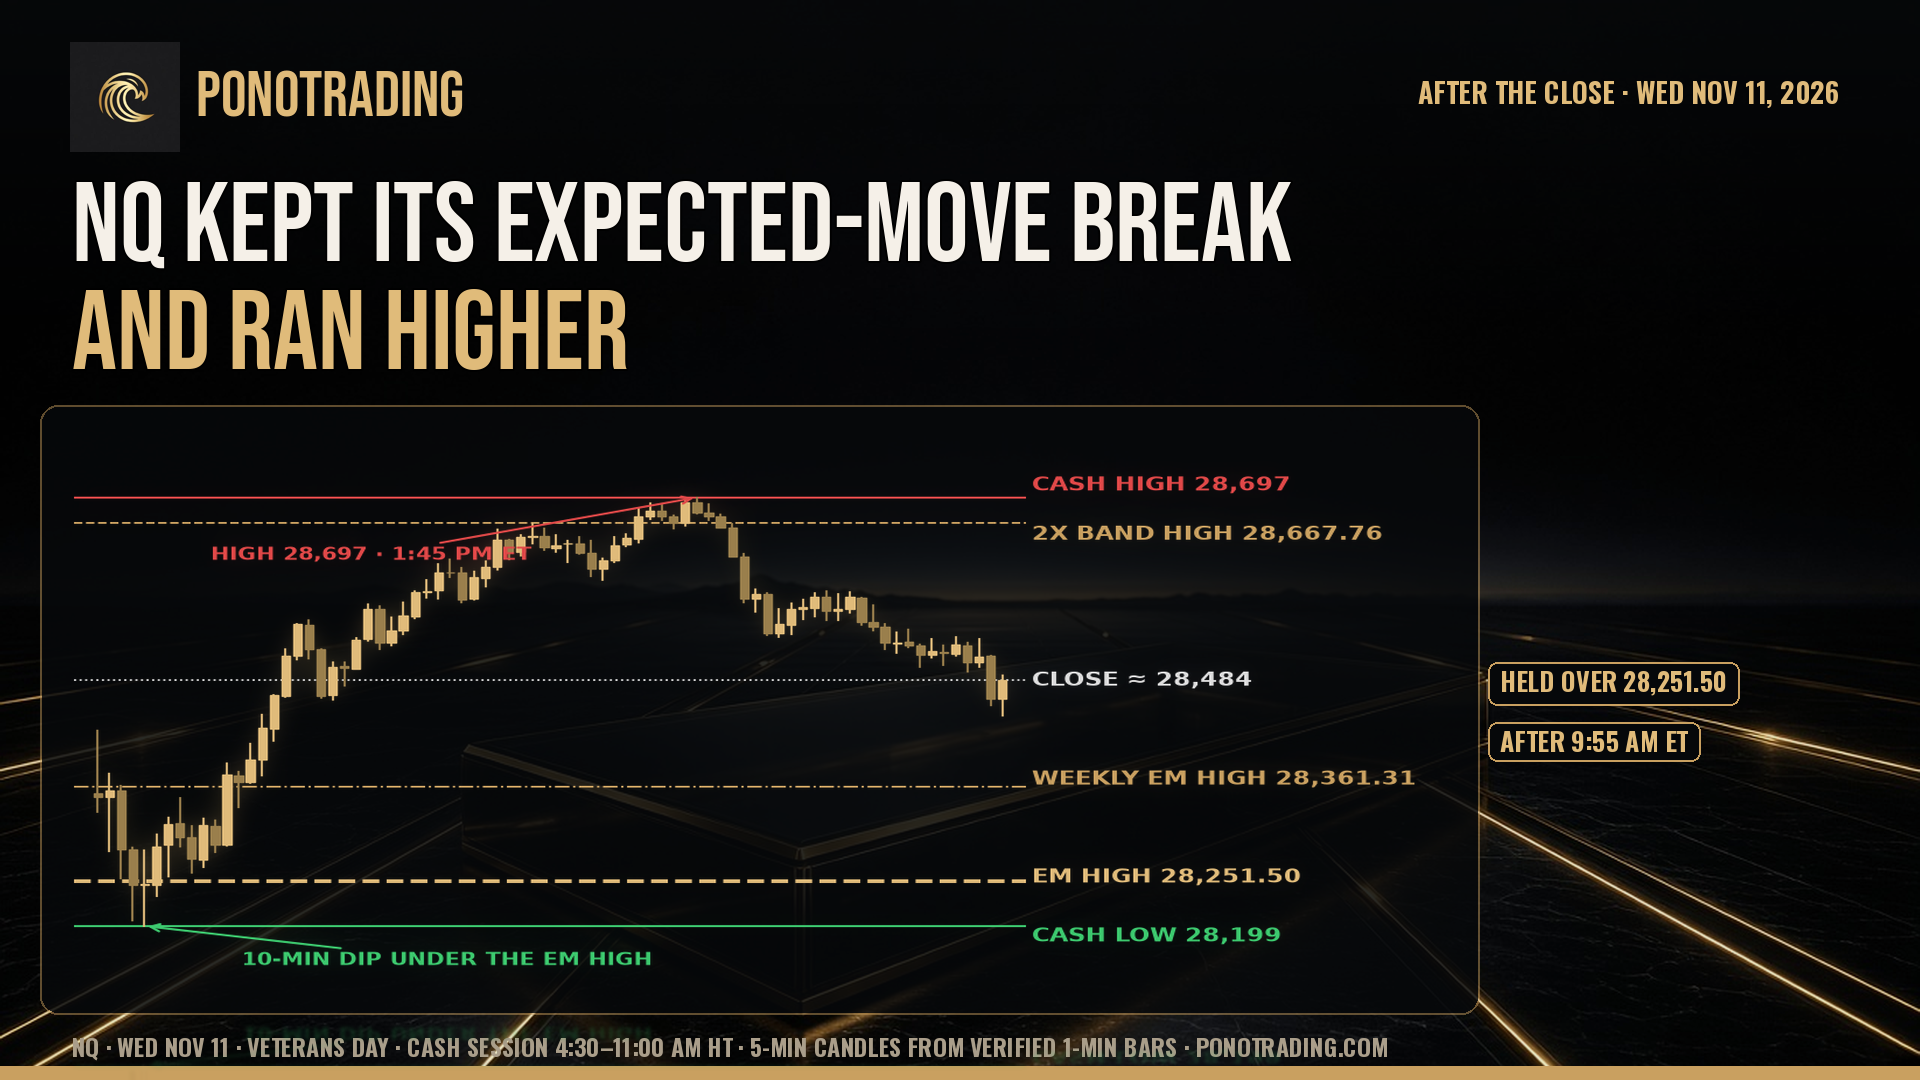
NQ Kept Its Expected-Move Break and Ran Higher
NQ kept this morning's break over its expected-move high. It dipped under for 10 minutes, then ran to its 2x band as AI stocks bounced. ES joined it. Scorecard, alert board, Thursday's PDM and the plan into PPI.