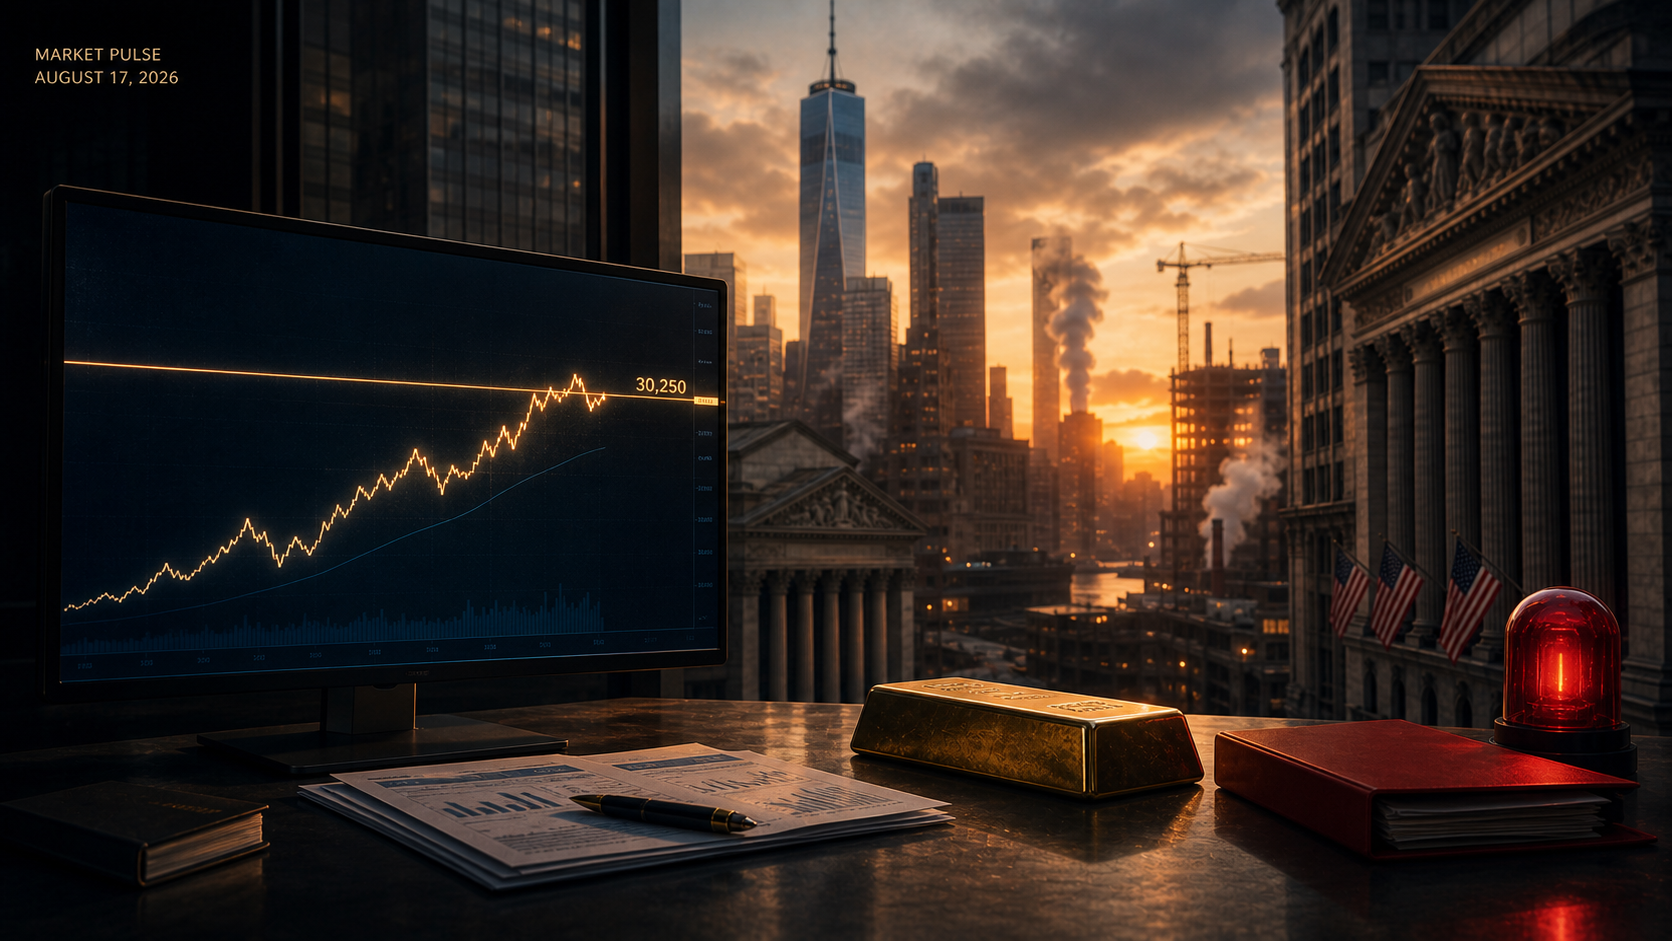
Nasdaq Tags Daily +1SD as Strong Factory Data Lifts Yields, Not Breadth
Empire manufacturing reached a four-year high, but NQ flinched as yields firmed and breadth lagged. The 30,250 Big Level now aligns almost exactly with daily +1SD.
Monday, August 17, 2026
The factory report beat. Nasdaq still flinched. That is the part traders should not ignore.
New York manufacturing activity accelerated to its strongest reading in more than four years, yet the first market response was not a clean risk-on breakout. NQ lost roughly 15 points in the five minutes after the 8:30 a.m. ET release, the 10-year Treasury yield edged toward 4.71%, and Dow futures remained the weak link.
At the same time, Nasdaq futures were testing a much bigger technical coincidence: 30,250, a PonoTrading Big Level, sat almost directly on Monday's modeled daily +1 standard-deviation boundary near 30,252.50.
That turns the morning into an acceptance test. Strong data can support the growth story, but hotter input costs and firmer yields can still punish an expensive index. The headline does not decide the trade. Price behavior at the boundary does.
What You Need to Know
- Empire manufacturing beat: the New York Fed's headline index rose to 20.6 from 15.6, its strongest reading in more than four years.
- The inflation detail was less friendly: prices paid climbed six points to 58.6, while supply availability worsened and delivery times lengthened.
- The immediate index reaction was mixed: from 8:29 to 8:35 a.m. ET, NQ fell about 15 points, ES slipped about 1.75 points, and RTY lost about 1.5 points.
- NQ opened at a statistical boundary: daily +1SD calculates near 30,252.50, almost exactly on the 30,250 Big Level.
- There is no red-folder U.S. release before the open today. Empire State manufacturing and the 10:00 a.m. NAHB Housing Market Index are meaningful, but they are second-tier events. Tuesday's housing, import-price, and industrial-production sequence carries the heavier scheduled risk.
The 8:30 Economic Result
| Empire State Manufacturing Survey | August | July | Market read |
|---|---|---|---|
| General business conditions | 20.6 | 15.6 | Strongest in more than four years |
| New orders | 17.3 | 22.2 | Continued solid growth, but slower than July |
| Shipments | 11.7 | 24.4 | Still expanding, with less momentum |
| Unfilled orders | 15.5 | 4.8 | Backlogs increased notably |
| Delivery times | 20.6 | 13.0 | Supply pressure intensified |
| Prices paid | 58.6 | 52.3 | Input-cost pressure accelerated |
| Prices received | 22.7 | 27.6 | Selling-price increases eased but remained elevated |
The headline was stronger than consensus and stronger than July. The internals explain why rates did not treat it as a free bullish signal.
Orders and shipments remained positive, employment continued to expand, and firms stayed optimistic about the next six months. But input prices accelerated, supply availability worsened, and delivery times lengthened substantially. That is a growth-positive report carrying an inflation-sensitive underside.
For index traders, that combination matters more than whether the headline printed green on an economic calendar.
The Market's First Verdict
The five-minute reaction after 8:30 was small, but it was informative because the markets did not confirm the same story.
| Market | 8:29 a.m. ET | 8:35 a.m. ET | Immediate change | Read |
|---|---|---|---|---|
| NQ | 30,236.00 | 30,220.75 | -15.25 | Growth strength did not override rate sensitivity |
| ES | 7,808.00 | 7,806.25 | -1.75 | Nearly balanced; no broad breakout confirmation |
| YM | 53,624 | 53,621 | -3 | Continued to lag the technology bid |
| RTY | 3,066.70 | 3,065.20 | -1.50 | Factory strength did not create immediate small-cap leadership |
| 10-year yield | 4.708% | 4.710% | +0.2 bp | Mild upward rate pressure |
| Gold | 4,441.70 | 4,443.40 | +1.70 | The hedge bid did not disappear |
This was not a violent rejection. It was a refusal to confirm the simplest narrative.
A cleaner risk-on response would have paired a stronger NQ with ES participation, improving Dow and Russell breadth, and contained yields. Instead, NQ remained the relative leader while YM and RTY stayed softer and the 10-year yield held near 4.71%.
Prior Session, Overnight Markets, and US Futures
Friday left the market with a split handoff. Nasdaq had already demonstrated that it could trade above 30,250, but it had not established durable acceptance there. The broader tape also carried a consumer warning after weak retail sales, even as falling volatility kept the move from becoming a liquidation event.
Friday's VIX close near 14.25 kept index volatility compressed heading into Monday. That supports orderly price discovery, but it also raises the information value of a failed boundary test: if NQ cannot hold 30,250 while protection remains relatively inexpensive, traders should not blame elevated fear premiums for the rejection.
Monday's overnight session pushed NQ to approximately 30,343, then returned it toward the 30,250 area before the cash open. ES reached roughly 7,824.50, while YM and RTY failed to preserve comparable strength.
| Contract | Friday reference | Overnight high | Overnight low | Pre-open area | Read |
|---|---|---|---|---|---|
| ES | 7,770.50 | 7,824.50 | 7,801.25 | 7,805-7,809 | Above Friday, below overnight expansion |
| NQ | 29,853.25 | 30,343.00 | 30,180.00 | 30,210-30,240 | Strongest index, testing the 30,250 decision area |
| YM | 53,871 | 53,807 | 53,585 | 53,600-53,640 | Relative weakness despite the factory beat |
| RTY | 3,052.80 | 3,079.90 | 3,061.40 | 3,064-3,067 | Above Friday, but unable to confirm the overnight high |
| Gold | 4,408.90 | 4,462.60 | 4,433.40 | 4,440-4,445 | Elevated while yields remained firm |
| WTI crude | 83.27 | 83.23 | 81.83 | 82.55-82.85 | Below Friday's reference, but still an inflation-sensitive input |
The useful distinction is leadership versus breadth. NQ can be strong while the market underneath it remains selective. That is not automatically bearish. It does mean a long thesis at 30,250 needs confirmation instead of admiration.
Today's Expected-Move Map
The following daily fields use Friday futures references and Friday closing volatility indexes. They are statistical context, not guaranteed targets or executable prices.
| Market | Daily -1SD | Friday anchor | Daily +1SD | Monday location |
|---|---|---|---|---|
| ES | 7,700.75 | 7,770.50 | 7,840.25 | Upper half, below +1SD |
| NQ | 29,454.00 | 29,853.25 | 30,252.50 | Testing +1SD and the 30,250 Big Level |
| YM | 53,387 | 53,871 | 54,355 | Below its anchor; breadth warning |
| RTY* | 3,011.97 | 3,052.80 | 3,093.63 | Above anchor, below +1SD |
| Gold | 4,342.60 | 4,408.90 | 4,475.20 | Upper half, below +1SD |
| WTI crude | 80.68 | 83.27 | 85.86 | Below anchor, inside the field |
RTY uses VXN as a conservative volatility proxy because a current RVX observation was unavailable in the delayed source feed.
NQ's confluence is the center of the plan. A tag of 30,250 is not automatically a short, and trading above +1SD is not automatically a breakout. The signal comes from whether price can build value above the boundary after the cash market adds liquidity.
Headlines, Economic Calendar, and Earnings
Today's scheduled U.S. calendar is lighter than the rest of the week.
| Time (ET) | Event | Status | Why it matters |
|---|---|---|---|
| 8:30 a.m. | Empire State Manufacturing Survey | 20.6 actual; complete | Strong growth with hotter input costs |
| 10:00 a.m. | NAHB Housing Market Index | Pending at publication | Tests builder confidence before Tuesday's housing data |
| 11:00 a.m. | New York Fed SCE Labor Market Survey | Scheduled | Adds labor expectations after recent employment weakness |
| 4:00 p.m. | Treasury International Capital data | Scheduled | Longer-term capital-flow context after the close |
There is no red-folder U.S. event in the pre-open window. Traders should not manufacture event risk where the calendar does not provide it. The more consequential scheduled sequence begins Tuesday with housing starts, building permits, import prices, industrial production, capacity utilization, and pending home sales. FOMC minutes follow Wednesday at 2:00 p.m. ET.
The earnings backdrop is consumer-heavy this week, with major retailers expected to update investors on demand, margins, and pricing power. That matters after Friday's retail-sales miss, but Monday's index trade should still be grounded in price, breadth, rates, and the 30,250 boundary rather than borrowed conviction from an earnings preview.
The Plan: Three Cash-Session Scenarios
1. NQ earns the breakout
NQ reclaims 30,250-30,253, holds above the zone on a retest, and begins building time above daily +1SD. ES holds above 7,801 and starts pressing back toward 7,824.50, while YM reclaims its Friday reference and RTY improves through the overnight middle.
That would show that buyers can absorb the rate pressure and turn the strong factory report into accepted growth leadership. The invalidation is not one red candle. It is a failed retest that returns NQ below the boundary and leaves breadth behind.
2. The +1SD tag becomes a rejection
NQ repeatedly fails at 30,250-30,253, loses 30,180, and cannot reclaim the overnight low area. ES breaks 7,801, while the 10-year yield stays firm and YM remains below its anchor.
That would make the overnight advance an excursion into a statistical edge rather than a confirmed breakout. The first downside objective is the upper portion of Friday's range, not an automatic trend-day collapse.
3. Housing data traps both sides
NQ rotates around 30,250 and ES remains inside 7,801-7,824.50 through the first half hour, leaving no clean acceptance. With NAHB scheduled for 10:00 a.m. ET, opening positions can be reduced or invalidated by a second information event.
Inside that box, patience is the professional position. Let the housing release pass, then trade the retest rather than the first algorithmic impulse.
The PonoTrading Take
Good data is not the same thing as good location.
Empire manufacturing strengthened. NQ also arrived at daily +1SD and a major round-number decision level while the 10-year yield pressed higher and breadth lagged. Both facts can be true at once.
Retail traders tend to choose one story and defend it. Professionals mark the boundary, define what acceptance looks like, and let the market show whether the headline deserves follow-through.
The level is 30,250. The edge is not predicting the first touch. The edge is knowing what must happen next.
Put the Decision Map on Your Screen
Use the PonoTrading Expected Move Tracker to place daily and weekly statistical boundaries beside the Big Levels before price reaches them. Then define the retest, invalidation, and maximum loss before the tape accelerates.
Open the PonoTrading Expected Move Tracker
Want the complete ecosystem with live market context, trading tools, education, and the community built around this process? Join Kahuna.
Bottom Line
The August Empire State Manufacturing Survey rose to 20.6, its best reading in more than four years, but input prices accelerated and the first index response remained mixed. NQ slipped roughly 15 points in the first five minutes, yields held near 4.71%, and YM continued to lag.
NQ's modeled daily +1SD sits near 30,252.50, almost directly on the 30,250 Big Level. Acceptance above that confluence with ES and breadth confirmation keeps the bullish path alive. Repeated failure there, followed by a loss of 30,180, turns the overnight strength into a rejected statistical extension.
The headline beat. The market still has to prove it.
Market observations were captured between 8:29 and 9:31 a.m. ET on Monday, August 17, 2026. Futures, volatility, yields, dollar, and commodity values are delayed references, not official settlements or executable quotes. Expected moves are model-derived estimates, not guarantees. Educational content only; futures involve substantial risk and this is not financial advice.
Sources
- Federal Reserve Bank of New York: August 2026 Empire State Manufacturing Survey
- Federal Reserve Bank of New York: August 2026 Economic Calendar
- National Association of Home Builders: Housing Market Index release schedule
- Associated Press: Futures mixed ahead of a major retail earnings week
- Yahoo Finance delayed market data
Related Articles
Quiet Monday. Nasdaq Already Spent the Easy Band.
FOMC week opens with no Tier-1 Monday print. NQ already through daily −1SD overnight off Friday’s 29,387 settle. CL reclaiming off $100.05. Wednesday owns the week.

Core Printed Hot. Oil Gave Back the Easy Band.
August CPI matched at +0.4% / 3.4%. Core +0.3% m/m / 2.4% y/y — hot on the month. CL through daily −1SD off the $102.48 settle. Equities reclaimed overnight. FOMC is next week.

Oil Already Spent the Band. PPI Printed Hot on the Year.
Crude already spent daily +1SD overnight on Middle East supply risk. NQ through daily −1SD. August PPI printed +0.4% m/m and +5.4% y/y — matched the month, a touch hot on the year. CPI is still Friday.