The Indexes Rallied, but Pono Algo Traded the Structure Beneath the Headline
Nasdaq rallied behind Nvidia while most S&P 500 stocks fell. See how the morning map resolved and how Pono Algo applied one risk framework across Asia, London, and New York.
The market rewarded traders who followed structure on Thursday, not traders who simply believed the headline.
Nasdaq surged behind Nvidia, yet most stocks in the S&P 500 still finished lower. That split created two different stories: a powerful index rally on the surface and a much less uniform market underneath it. The better opportunity was not guessing which story would win. It was defining entries, targets, and risk before price forced a decision.
Today's Pono Algo trades captured that distinction across Asia, London, and New York. Pono Algo took the documented executions across multiple prop-firm accounts in live market conditions. Three separate MNQ setups reached their planned targets, and none required more than approximately 53% of the stop risk available to the trade. Together, they show why process matters more than chasing a loud close.
Official Close: Leadership Without Full Participation
The Nasdaq Composite gained 1.6% to close at 26,541.35, while the S&P 500 added 0.7% to 7,730.99. The Dow rose 0.2% to 53,569.44, and the Russell 2000 gained 0.3% to 3,014.34.
Those green closes conceal the session's most important tension. Nvidia rallied approximately 8.7% and supplied the strongest lift to the S&P 500, more than offsetting declines in the majority of the index's stocks. Salesforce, CrowdStrike, and Okta also delivered powerful earnings reactions, but Thursday remained a concentrated technology-led advance rather than a clean everything-rally.
That distinction matters for Friday. Strong leadership can keep the indexes elevated, but narrow participation leaves less room for error if the leaders stop carrying the load.
The Morning Plan Earned Confirmation
The morning Market Pulse framed Thursday as a confirmation session, not a celebration session. Nvidia had already passed its company test. The open question was whether NQ could accept above 29,617.89 while YM reclaimed 53,521 and RTY held above 3,010.10.
The bullish path largely played out. NQ finished near 29,632 after trading as high as approximately 29,708, ending just above its upper daily expected-move band. ES reached roughly 7,752.50, almost exactly testing its 7,751.22 upper band, before finishing back inside the field near 7,733. YM and RTY both reclaimed their anchors.
The important qualification is breadth. The futures map confirmed the bullish scenario, but the cash market did not deliver uniform participation. This was a successful acceptance trade led by technology, not proof that every part of the market became equally healthy.
The Expected-Move Map Defined the Session
| Contract | Daily Anchor | Daily 1SD High | Late-Session Read | What Happened |
|---|---|---|---|---|
| ES | 7,690.00 | 7,751.22 | 7,732.75 | Tested the upper band, then returned inside |
| NQ | 29,289.50 | 29,617.89 | 29,631.75 | Accepted near and finished just above the upper band |
| YM | 53,521 | 53,947.10 | 53,603 | Reclaimed the anchor but lagged technology |
| RTY | 3,010.10 | 3,034.06 | 3,018.20 | Held above the anchor without a broad breakout |
The map did not predict the close. It defined where the session had to prove itself. NQ's acceptance around 29,617.89 separated a durable earnings response from a failed excursion. ES touching its upper band and returning inside showed that the broad index participated without matching Nasdaq's extension. YM and RTY clearing their anchors improved the tape, but their modest closes warned against treating the move as indiscriminate risk-on strength.
Earnings Winners Carried the Tape
Nvidia remained the session's central force after reporting fiscal second-quarter revenue of $96.2 billion and guiding fiscal third-quarter revenue to $108.0 billion, plus or minus 2%. Its stock closed near $227.98, up approximately 8.7%.
Software added real support. Salesforce closed approximately 22.6% higher, CrowdStrike gained roughly 20.5%, and Okta rose about 28.6%. Those reactions confirmed continued demand across enterprise software, cybersecurity, and identity. They also reinforced the concentration problem: a small group of exceptional earnings winners did much more work than the headline index closes suggest.
After the bell, Marvell reported record fiscal second-quarter revenue of $2.739 billion, up 37% year over year, with Data Center revenue growth of 46%. The company raised its fiscal 2027 and 2028 revenue outlooks and guided third-quarter revenue to $3.150 billion, plus or minus 5%. Its shares traded roughly 3% below the regular-session close in the early after-hours reaction, making the conference call and overnight response an immediate test of how demanding AI expectations have become.
Pono Algo Traded Three Different Paths to Structure
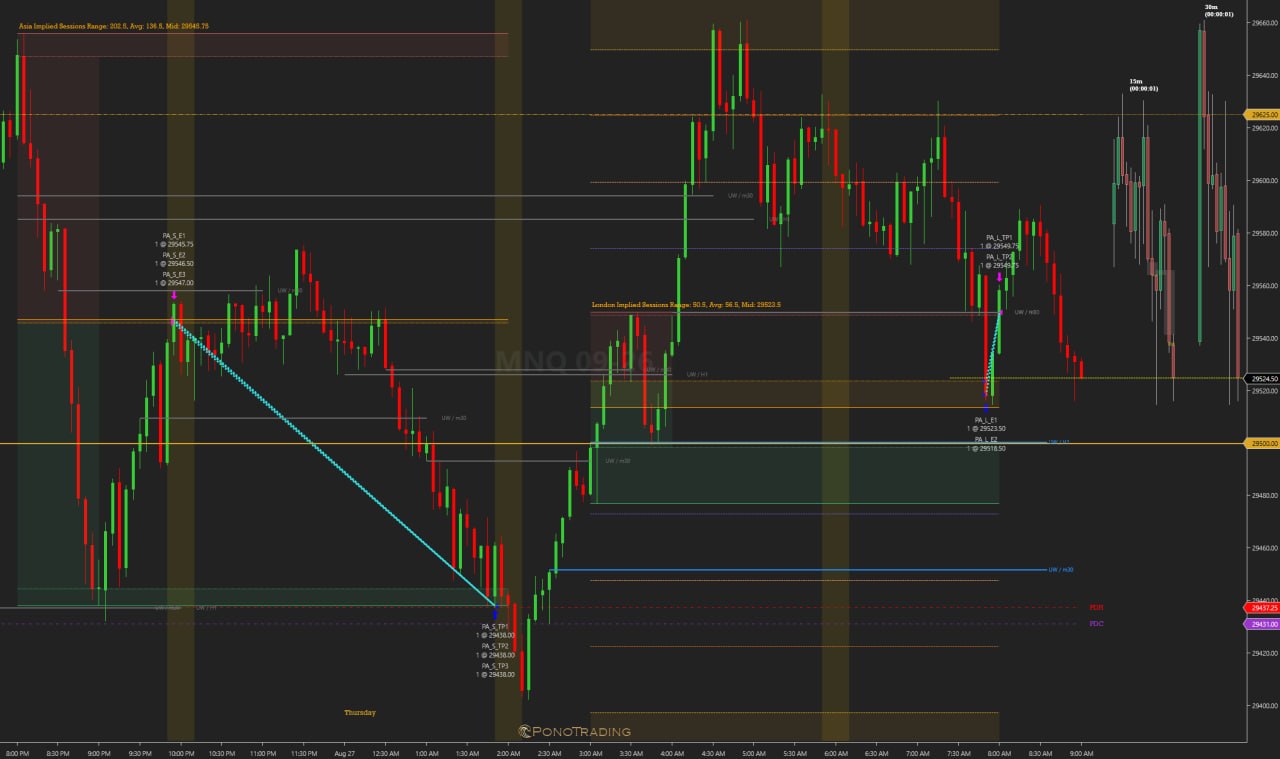
Thursday's MNQ five-minute Pono Algo executions produced three completed targets across three sessions and were taken across multiple prop-firm accounts. The common element was not direction. Asia was short, while London and New York were long. The common element was a repeatable process: wait for directional confirmation, allow price to retrace into planned entries, improve the average through controlled scaling when needed, and keep the stop and target defined from the beginning.
Asia: Let the Retracement Come to the Trade
The Asia short filled all three planned entries at an average price of 29,545.75 and reached its 29,438.00 target. The documented execution produced a $646.50 gross result before commissions, with approximately $160.50 of maximum adverse excursion. That used about 52.5% of the permitted stop risk and represented approximately 4.0 times the actual drawdown. The trade lasted about three hours and 50 minutes.
The transferable lesson is patience. The initial downside move was not chased. Price retraced into the structured entry area, filled progressively better prices, and then continued toward the planned target.
London: The Best Trade May Need Less
The London long filled two of three planned entries at an average price of 29,521.00 before reaching its 29,549.75 target. The documented execution produced a $115.00 gross result before commissions, with approximately $19.00 of maximum adverse excursion. It used about 45.2% of permitted stop risk and delivered roughly 6.1 times the actual drawdown in about 10 minutes.
The third entry was never needed. That matters because a scaling plan is not an obligation to use every order. When price confirms quickly, the structure should be allowed to work without forcing additional exposure.
New York: Scaling Improved the Decision
The New York long filled all three planned entries at an average price of 29,529.42 and reached its 29,622.25 target. The documented execution produced a $557.00 gross result before commissions, with approximately $112.00 of maximum adverse excursion. It used about 50.2% of permitted stop risk and produced approximately 5.0 times the actual drawdown over roughly 15 minutes.
New York delivered the deepest retracement of the three long examples. Planned scaling improved the average entry before price reversed toward the target. The value was not predicting the exact low. It was knowing where participation remained valid and how much risk the setup was allowed to consume.
What the Three Executions Actually Show
Combined, the three documented executions filled eight entries and produced approximately $1,318.50 in gross results before commissions. The largest trade-level drawdown was about $160.50, and no trade used more than approximately 53% of its permitted stop risk. The run demonstrates the behavior Pono Algo is designed to support: objective session structure, directional confirmation, planned retracement entries, controlled scaling, predetermined targets, and risk defined before the trade begins.
The market changed direction across the three sessions. The process did not. That is the point.
Cross-Asset Signals Lowered Stress but Did Not Remove Risk
Volatility eased as the technology rally held. VIX finished near 14.51 from 15.21, while VXN fell to roughly 20.24 from 21.42. OVX eased to approximately 46.22, and GVZ was near 26.80. The decline in equity volatility supported the bullish acceptance path, but VXN remained high enough to respect Nasdaq's larger intraday range.
The 10-year Treasury yield held near 4.67%, and the dollar index was little changed near 99.14. Gold pushed into the upper portion of its daily field near 4,658, while crude traded near $83.47 after testing approximately $84.27, close to its $84.25 upper daily band.
The combined message was constructive but not carefree: volatility backed away, yet rates stayed firm and both crude and gold pressed the upper parts of their maps. Friday's traders inherit a market with strong technology momentum and unresolved macro sensitivity.
What Held, What Failed, and What Changed
NQ acceptance above 29,617.89 held. ES reached its upper-band test. YM and RTY reclaimed their anchors. The morning bullish scenario therefore earned confirmation rather than merely benefiting from hindsight.
What failed was the assumption that powerful index gains would automatically produce broad participation. Most S&P 500 stocks still declined. The market rewarded leadership selection and disciplined execution more than broad exposure.
What changed after the bell was the burden of proof. Nvidia and the software winners validated demand, but Marvell's initially negative reaction showed that strong reported growth may not be enough when expectations are already elevated. The next question is whether buyers defend the AI complex when the results are good but the first reaction is not.
Asia Handoff: Do Not Confuse Extension With Fresh Opportunity
Asia inherits NQ just above Thursday's 29,617.89 upper daily band, not at the beginning of the move. That makes acceptance more important than excitement. Holding above the band would preserve the bullish structure, while a sustained move back below it would warn that the U.S. extension is being unwound.
Marvell is the immediate company-specific read-through. If its after-hours weakness stabilizes while Nvidia holds its earnings gap, Asia can treat the AI trade as differentiated rather than broken. If both begin losing support, the narrow leadership that powered Thursday becomes a source of downside risk.
The practical lesson from the Pono Algo examples applies directly: do not chase the first move. Let price retrace into a defined area, identify the invalidation, and decide the risk before entry.
London Handoff: Rates and Breadth Must Join the Conversation
London inherits a stronger Nasdaq, a firmer 10-year yield near 4.67%, a dollar near 99.14, crude near the top of its daily field, and a U.S. market that rallied without broad internal confirmation. European technology can validate the leadership theme, but broader cyclicals and financials must participate before the move deserves a full risk-on label.
Watch whether ES can regain and hold the 7,751.22 area after Thursday's test, whether NQ remains accepted above 29,617.89, and whether Russell participation improves beyond its modest anchor reclaim. Failure at those levels would not erase the earnings wins, but it would turn Thursday's extension into a less favorable place to initiate risk.
Friday's larger macro catalyst is Federal Reserve Chair Kevin Warsh's scheduled Jackson Hole keynote at 10:00 a.m. ET. London traders should expect rates and the dollar to carry more influence as the speech approaches and avoid assuming Thursday's technology reaction settles the policy question.
Bottom Line
Thursday proved that a strong headline and a good trade are not the same thing. Nvidia and the software winners lifted the indexes, but narrow breadth kept selection and risk control essential. The morning expected-move map identified the acceptance test. Pono Algo's Asia, London, and New York examples showed how a structured process can adapt when the market changes direction.
If you want to replace improvised entries with a framework built around confirmation, planned retracements, controlled scaling, and defined risk, join the PonoTrading Kahuna community and follow the continued development of Pono Algo. You will get access to PonoTrading tools, education, and community resources designed to help you approach the market with structure instead of guesswork.
This material is for educational purposes only and is not financial advice. Futures trading involves substantial risk of loss. Define invalidation before entry and use risk capital only.
Performance Disclosure
The documented Pono Algo trades occurred in live market conditions across multiple prop-firm accounts. Results are shown gross before commissions and account-specific fees; prop-firm rules and execution conditions vary. Past results do not guarantee future performance, and futures trading involves substantial risk of loss.
Related Articles
Short Board, Long Weekend
PonoTrading's board sent 14 hourly setups and no Daily or Weekly, and NQ's 30984.5 zone held twice. The S&P rose 0.6% to 7,811.54 for its first gain since its record, the Dow added 423 points, and Michigan sentiment fell to 46.3. Cash bonds are closed Monday.
Long Bond Holds, Chips Fold
The 30-year sold at 5.618%, the highest since 2000, with a 2.54 bid-to-cover, and the 10-year fell back to about 5.23%. Chips sank on an OpenAI revenue report: Nasdaq 27,193.34 (−1.3%), S&P 7,765.36 (−0.5%), Dow +0.1%, Russell flat. WTI settled $91.49 after Trump ruled out Iran strikes before the midterms. Morning call scored, Friday levels, Asia/London handoff.
High Tide for Yields, Low Tide for Small Caps
The 10-year hit 5.35%, highest since 2002, then a strong 10-year auction (5.300%, 2.77 bid-to-cover) stopped the selling. S&P 7,801.77 (−0.2%), Russell 2,793.20 (−1.3%). WTI settled $88.28 despite a 3.2M-barrel draw. ES and NQ held their expected-move lows; RTY flushed to the 2× band. Morning call scored, Thursday levels, Asia/London handoff.